
On 26 October 2026, the Capital Markets Board of Türkiye ("CMB") raised the financial thresholds for qualified investor status. For many companies, this makes investing in venture capital funds much harder, just weeks before an important tax deadline.
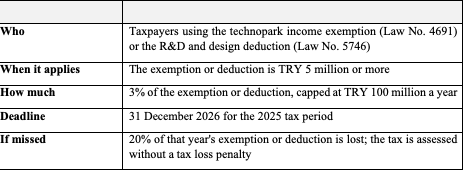
Companies using the technopark income exemption or the R&D and design deduction must invest 3% of that benefit in venture capital. For the 2025 tax period, the deadline is 31 December 2026. Here is what changed and what it means in practice.
1. What Changed?
Three changes matter most:
• Higher thresholds. To qualify on the basis of financial assets, an investor now needs TRY 50 million instead of TRY 10 million. The trading volume threshold rises from TRY 5 million to TRY 25 million per quarter, with at least 10 transactions. Legal entities must meet two of three new criteria: TRY 2.5 billion in total assets, TRY 4.5 billion in net revenue or TRY 250 million in equity.
• No more fund exception. Investors in venture capital investment funds ("VCIFs") and real estate investment funds had been exempt from the earlier increase. That exception is gone. For VCIF investors relying on financial assets alone, the threshold has risen fifty-fold, from TRY 1 million to TRY 50 million.
• Existing status must be proven again. Investors who qualified under the old thresholds must show their investment firm that they meet the new ones. Until they do, they can keep or sell their holdings but cannot buy more.
If your company has already committed capital to a VCIF, ask the portfolio management company in writing how future capital calls will be handled. The decision has no transition rule for them.
2. The 3% Obligation at a Glance
3. Which Routes Still Work?
The obligation can be met in three ways, but the CMB decision does not affect them equally.
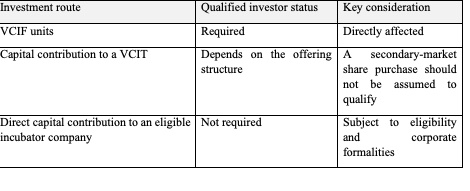
Direct investment in an eligible incubator company generally offers a route that does not require qualified investor status. Capital contributions to certain venture capital investment trusts may also be possible without that status, depending on the trust's offering structure and applicable requirements.
4. Investing in an Incubator Company: Three Checks
1. Confirm incubator status. Being in a technopark is not enough. The company must be in an incubation centre, be no more than three years old and meet the other conditions of the Implementation Regulation. Get written confirmation from the technopark management company as of the investment date.
2. Put in new capital. The law requires a capital contribution, so buying existing shares from founders does not count on its own. Invest at incorporation or through a capital increase. A 2025 private ruling confirms that share premium can count towards the amount and that no minimum holding period applies, but it should be read in light of its specific facts. Check the corporate and tax treatment of any share premium.
3. Don't mix up regimes. The separate capital support deduction under the Implementation Regulation, available until 31 December 2028, requires a four-year holding period. Its rules do not apply to the 3% obligation, and vice versa.
5. What Should You Do Now?
• Planning to use a VCIF? Confirm now that you meet the new thresholds and check the fund manager's acceptance process.
• Can't meet the thresholds? Consider a direct investment in an incubator company and start early to leave time for the corporate steps.
References
1. Press Release on the Update of the Qualified Investor Financial Asset Threshold and the VCIF/REIF Exception, Capital Markets Board of Türkiye, 26 October 2026. spk.gov.tr
2. Guidelines on Investment Services and Activities and Investment Firms, i-SPK.37.10 (26 October 2026, No. 75/1899), in particular Section BB on Professional Clients and Qualified Investors, pp. 52–55. Capital Markets Board of Türkiye. spk.gov.tr
3. Communiqué No. III-39.1 on the Principles of Establishment and Operation of Investment Firms, Arts. 30–32; Communiqué No. II-5.2 on the Sale of Capital Market Instruments, Art. 9. mevzuat.spk.gov.tr
4. Law No. 4691 on Technology Development Zones, Additional Article 3. Revenue Administration. gib.gov.tr
5. Law No. 5746 on Supporting Research, Development and Design Activities, Art. 3(14). Revenue Administration. gib.gov.tr
6. Presidential Decree No. 10803, 31 December 2025, Official Gazette No. 33124 (5th Duplicate), effective 1 January 2026. gib.gov.tr
7. Technology Development Zones Implementation Regulation, Arts. 15, 35(3)(g) and 35/C. mevzuat.gov.tr
8. Private Ruling No. E-38418978-125[4691-24]-..., Ankara Tax Office Directorate, 26 November 2025. gib.gov.tr
9. Corporate Tax Law No. 5520, Art. 5(1)(ç). istanbul.gib.gov.tr
10. Communiqué No. III-48.3 on Principles Regarding Venture Capital Investment Trusts, Art. 12. lexpera.com.tr
Author
Özgür Karadağ